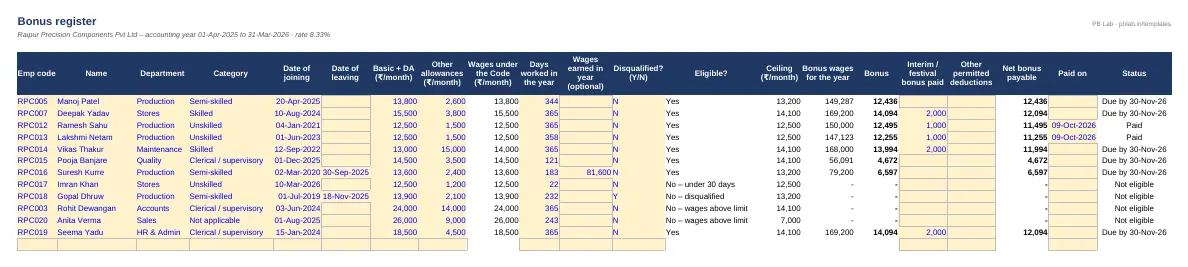
Bonus under the Code on Wages
From 21 November 2025, statutory bonus is governed by Chapter IV of the Code on Wages, 2019, which replaced the Payment of Bonus Act, 1965. It applies to establishments employing 20 or more persons. An employee is eligible if their wages are up to the notified limit – ₹21,000 a month – and they worked at least 30 days in the accounting year. The minimum bonus is 8.33% of wages or ₹100, whichever is higher, and the maximum is 20%.
The calculation ceiling
Bonus is not worked out on the full wage. Under notifications issued on 25 August 2026 (effective 21 November 2025), where an eligible employee's wages are more than ₹7,000 a month, bonus is calculated as if the wage were ₹7,000 or the minimum wage, whichever is higher. Since minimum wages are now above ₹7,000 almost everywhere, the minimum wage for the employee's category usually sets the ceiling. Practice differs on whether the State or Central minimum wage applies, so the template lets you enter the rate you use for each category.
What counts as wages
Under the Code, wages mean basic pay, dearness allowance and retaining allowance. Allowances such as HRA, conveyance and overtime are excluded – but if the excluded items are more than 50% of total remuneration, the excess is added back. The register applies this 50% rule automatically from basic + DA and other allowances, and uses the result both for the ₹21,000 eligibility test and for the bonus.
Allocable surplus, set-on and set-off
Whether you pay more than 8.33% depends on profits. The allocable surplus is 60% of the available surplus (67% for a company that hasn't arranged to pay dividends in India). If it is more than the minimum bonus, the rate rises up to 20%; any excess above 20% is carried forward as set-on, and if the minimum bonus is more than the surplus, the shortfall is carried forward as set-off – each for up to four years. The Pro edition works this out from your profit figures.
Deductions and the deadline
Interim bonus or customary festival bonus paid during the year can be deducted from the statutory bonus, as can amounts for financial loss caused by the employee's misconduct. Employees dismissed for fraud, violent behaviour, theft, misappropriation, sabotage or sexual harassment are disqualified. Bonus must be paid within eight months of the end of the accounting year – by 30 November 2026 for 2025-26.
Written by Prakash Bagchi, finance professional and founder of PB Lab. Last reviewed .