Who has to pay advance tax
If your tax for the year, after TDS and TCS, is ₹10,000 or more, you pay it during the year as advance tax rather than at the end. Resident senior citizens (60 or more) with no income from business or profession are exempt. Salaried people usually have enough TDS, but rent, interest, capital gains, consulting fees or a side business can make advance tax due.
Due dates and instalments
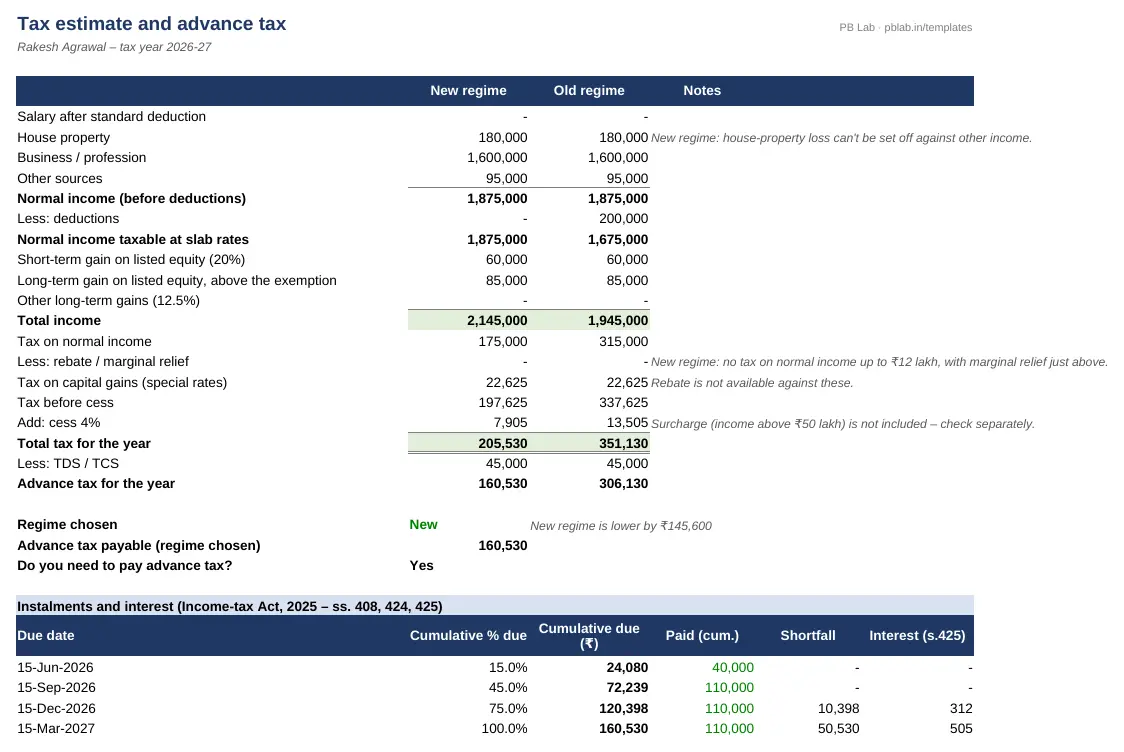
Under the Income-tax Act, 2025, which applies from tax year 2026-27, the schedule is unchanged: 15% of the year's tax by 15 June, 45% by 15 September, 75% by 15 December and 100% by 15 March. If you declare business or professional income under the presumptive scheme (old sections 44AD and 44ADA), you can pay the whole amount in one instalment by 15 March. Capital gains or dividends that arise after a due date can be covered in the later instalments without interest for the earlier ones.
How the tax is worked out
The calculator applies the 2026-27 slabs: in the new regime, nil up to ₹4 lakh, then 5% to 30% in ₹4 lakh steps above that, with a ₹75,000 standard deduction on salary and a rebate that makes normal income up to ₹12 lakh tax-free (with marginal relief just above). The old regime uses the ₹2.5 / 3 / 5 lakh exemption limits by age, deductions such as investments and health insurance, and a rebate up to ₹5 lakh.
Capital gains are taxed separately at special rates: 20% on short-term gains from listed shares and equity funds, and 12.5% on long-term gains, with the first ₹1.25 lakh of long-term gains on listed equity exempt. The rebate is not available against these gains. 4% health and education cess is added; surcharge for incomes above ₹50 lakh is not included.
Interest if you pay late or too little
Two kinds of interest apply. For deferment of instalments (old section 234C), you pay 1% a month on the shortfall – for three months for the June, September and December instalments and one month for March. There is no interest if at least 12% is paid by June and 36% by September. For default (old section 234B), if less than 90% of the tax is paid by 31 March, interest of 1% a month runs from April until you pay. The Computation sheet estimates both from the payments you enter.
Free vs Pro
The free edition does the full calculation for both regimes with instalments and interest. The Pro edition adds a quarterly re-estimate, because income rarely turns out as planned in June, and a challan log with BSR codes and serial numbers that you need when filing the return.
Written by Prakash Bagchi, finance professional and founder of PB Lab. Last reviewed .