TDS under the Income-tax Act, 2025
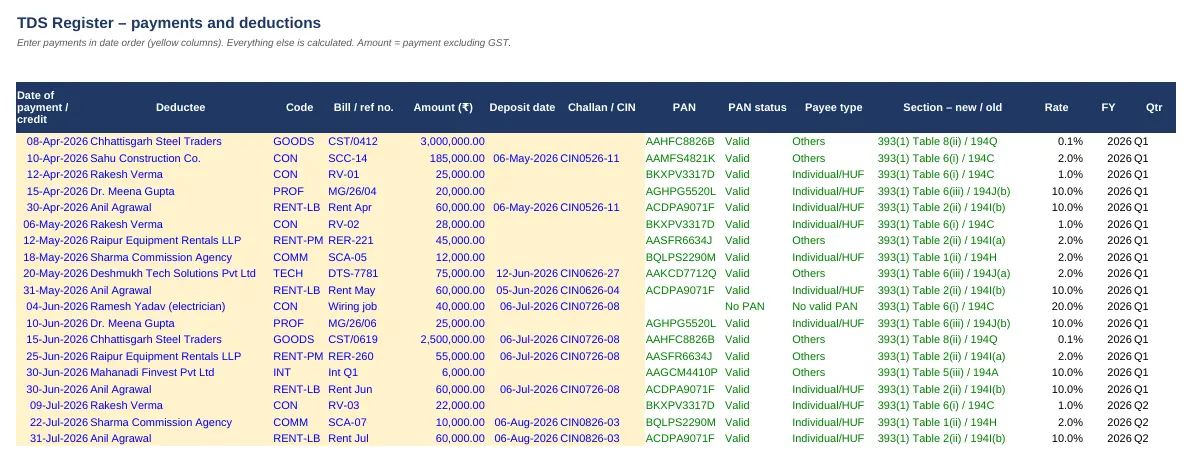
From 1 April 2026 the Income-tax Act, 2025 replaces the 1961 Act. TDS provisions that were spread across sections 192 to 196 are now consolidated in section 393, organised as tables. For example, payments to contractors (old 194C) are at Table serial 6(i), professional fees (old 194J(b)) and technical fees (old 194J(a)) at 6(iii), commission or brokerage (old 194H) at 1(ii), rent (old 194-I) at 2(ii), interest other than on securities (old 194A) at 5(iii), and purchase of goods (old 194Q) at 8(ii).
Because most people still think in the old section numbers, the tracker shows the new reference and the old section side by side for every entry.
Thresholds and the catch-up rule
Several sections have both a single-payment and an annual limit. For contractors, TDS applies when a single payment exceeds ₹30,000 or the total for the year exceeds ₹1,00,000. When the annual limit is crossed, TDS is due on the whole amount paid during the year — including earlier bills on which nothing was deducted. The register keeps a running year-to-date total for each payee and section and applies this catch-up automatically on the bill that crosses the limit.
Other common thresholds in the Section Master include ₹50,000 for professional or technical fees, ₹20,000 for commission, ₹50,000 per month for rent, ₹10,000 for interest from non-bank payers and ₹50 lakh for purchase of goods. They are editable inputs, so check them against the law before you rely on them.
No PAN, higher rate
If the payee has not furnished a PAN, section 397(2) requires deduction at the higher of the normal rate or 20% (5% for purchase of goods). The Deductees sheet checks the PAN format and reads the payee type from its fourth character — P for an individual, H for an HUF, anything else is treated as 'others' — so the right rate is picked without manual selection.
Due dates, interest and returns
Tax deducted by a non-government deductor is deposited by the 7th of the following month; for deductions in March the due date is 30 April. Interest under section 398 is 1% per month or part of a month from the date tax was deductible to the date it was actually deducted, and 1.5% per month or part from the date of deduction to the date of deposit. The register works out the due date and interest for each line.
Quarterly statements have new numbers too: Form 140 replaces Form 26Q for resident non-salary TDS, Form 138 replaces 24Q for salary, Form 144 replaces 27Q for non-residents, and Form 131 replaces Form 16A as the deductee's certificate. The register tags every entry with its quarter so filing is easier.
What the tracker doesn't cover
It is built for resident, non-salary payments. Salary TDS, payments to non-residents, lower-deduction certificates and TCS are outside its scope. Rates and thresholds change — always confirm against the Act, the rules and CBDT notifications, or with your tax adviser.
Written by Prakash Bagchi, finance professional and founder of PB Lab. Last reviewed .