What a society maintenance register needs
A housing society or RWA collects maintenance from every flat and pays for security, housekeeping, common electricity, lifts, water and repairs. Members want to know what they owe; the committee wants to know who hasn't paid and whether collections cover expenses. This workbook keeps the three things that answer those questions together: what each flat is billed, what has been received, and what has been spent.
How the monthly charge is worked out
Choose per sq ft (for example ₹3 a sq ft a month) or a fixed amount per flat. Add parking per slot and a sinking fund contribution per flat, and a non-occupancy charge for flats let out to tenants, as a percentage of maintenance. The Members sheet shows the breakdown for each flat. One-off levies such as a painting fund go in 'Other charges this year', and arrears from last year in 'Opening dues'.
Dues, interest and defaulters
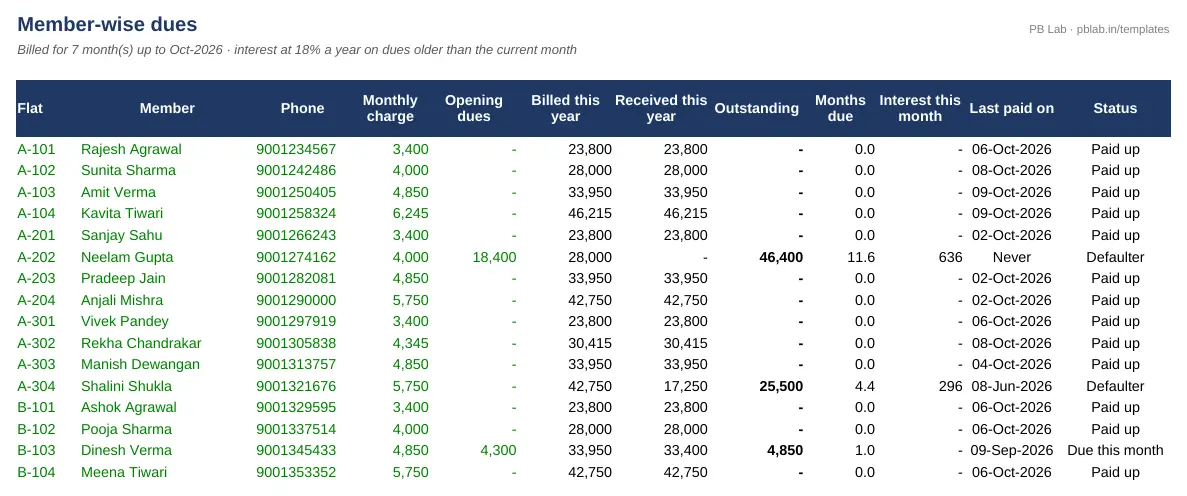
For each flat, Member Dues adds opening dues and the charges billed so far this year, deducts what has been received and shows the outstanding amount and how many months it represents. Interest for the month is worked out at your rate on dues older than the current month. Flats with dues of three months or more (you can change this) appear on the Defaulters list, largest first.
Interest, non-occupancy charges and how defaulters are dealt with must follow your bye-laws and general body resolutions, and some States cap them – for example, Maharashtra's model bye-laws allow interest of up to 21% a year and non-occupancy charges of up to 10% of service charges. A society cannot cut water or electricity to recover dues.
GST and income tax for societies
GST does not apply if the society's turnover is up to ₹20 lakh a year, or if a member's contribution is up to ₹7,500 a month. If both limits are crossed, GST at 18% applies; CBIC's view is that it is on the whole amount, while the Madras High Court has held that only the excess is taxable. The Settings sheet flags when both limits are crossed. Members' contributions are not taxable income under the principle of mutuality, but interest on the society's deposits and income from outsiders, such as mobile towers or hall hire, is.
Free vs Pro
The free edition has everything needed to keep the accounts: members, receipts, expenses, dues, defaulters and monthly accounts. The Pro edition adds printable maintenance bills and receipts with the amount in words, and WhatsApp reminders for defaulters.
Written by Prakash Bagchi, finance professional and founder of PB Lab. Last reviewed .